Case Study: Scottsdale Cash-Out Refinance Success in 2026
Published on May 2, 2026
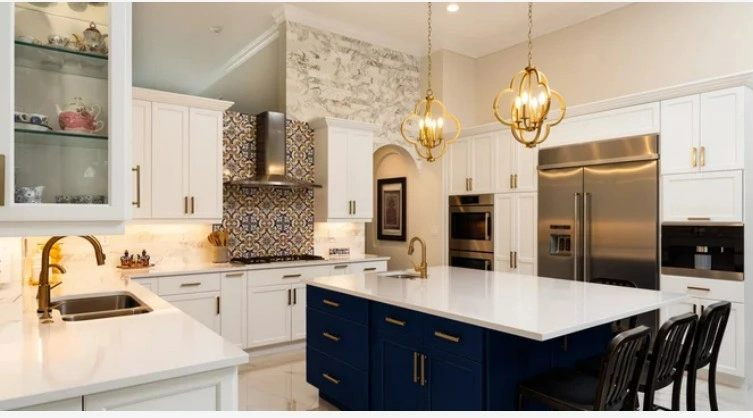
In the evolving landscape of the 2026 Arizona real estate market, homeowners in Scottsdale find themselves in a unique position. While mortgage interest rates have stabilized in the low-to-mid 6% range—higher than the historic lows of 2020—property values in the Valley have continued their steady climb. This has created a massive reservoir of "tappable equity" for long-time residents.
This case study explores a real-world scenario of a Scottsdale family (we'll call them the "Millers" to protect their privacy) who faced a dilemma common to many households this year: How do you access your wealth without wrecking your monthly budget?
The Millers successfully navigated a cash-out refinance that not only funded a luxury kitchen renovation but also eliminated high-interest debt, ultimately improving their monthly cash flow. Here is a deep dive into how they did it, the math behind the move, and why this strategy is becoming increasingly popular in 2026.
The Client Profile: Living in the "Magic Zip Code"
The Millers live in the highly sought-after 85254 zip code, often called the "Magic Zip Code" because it features Scottsdale addresses with Phoenix taxes and services. They purchased their home in 2019, just before the pandemic market surge.
- Home Purchase Price (2019): $525,000
- Current Estimated Value (2026): $980,000
- Outstanding Mortgage Balance: $340,000
- Current Interest Rate: 3.75% (Fixed 30-Year)
- Credit Score: 720
On paper, the Millers were doing well. They had over $600,000 in equity. However, like many families dealing with the inflation spikes of 2023-2025, their day-to-day liquidity was tight.
The Challenge: The "Golden Handcuffs" of a Low Rate
The Millers had two primary financial stressors pushing them to act:
1. The Need for a Renovation
Their 1990s-built home still had its original kitchen—honey oak cabinets, tile countertops, and older appliances. In a neighborhood where renovated homes were selling for over $1.2 million, their outdated kitchen was a drag on their property value and their enjoyment of the home. They received quotes for a "Scottsdale Standard" remodel (white oak cabinetry, quartz waterfall island, Wolf/Sub-Zero appliances) coming in at approximately $75,000.
2. The High-Interest Debt Trap
Over the past few years, the Millers had accumulated significant consumer debt. Between medical bills, inflation-related living costs, and a few family vacations, they were carrying:
- Credit Card Debt: $35,000 at an average APR of 24.99%
- Personal Loan: $15,000 (used for a previous roof repair) at 11.5%
- Total Non-Mortgage Debt: $50,000
Their monthly minimum payments on this debt alone were suffocating, totaling nearly $1,400 per month.
The Dilemma: They needed $125,000 cash ($75k for the kitchen + $50k to pay off debt). But they were terrified of losing their 3.75% mortgage rate. This phenomenon, known as "rate lock" or "golden handcuffs," prevents many homeowners from making rational financial moves because they are hyper-focused on the interest rate percentage rather than the total monthly cash outflow.
The Options Analysis
We sat down with the Millers to compare three potential paths forward. Understanding these options is crucial for any Arizona homeowner in a similar boat.
Option A: The HELOC (Home Equity Line of Credit)
A HELOC would allow them to keep their primary mortgage at 3.75% and take out a second loan for the $125,000.
- Pros: Keeps the first mortgage intact.
- Cons: HELOC rates in 2026 are variable and tied to the Prime Rate. Currently, Prime is around 8.5%, putting most HELOCs at 9.5% to 10.5%. Furthermore, the payment is often interest-only for the first 10 years, meaning the principal balance never goes down unless you voluntarily pay extra.
- Result: Adding a $125,000 HELOC at 10% would add roughly $1,040/month in interest-only payments, on top of their existing obligations.
Option B: Personal Loans/Construction Loans
Unsecured loans for the kitchen were quoting around 12-15% interest with short repayment terms (5-7 years). This would skyrocket their monthly payments, making it unaffordable.
Option C: The Strategic Cash-Out Refinance
This option involved refinancing the entire $340,000 balance plus the $125,000 cash-out needed, resulting in a new loan of roughly $465,000 (plus closing costs).
- Pros: Fixed rate for 30 years. Eliminates the high-interest credit card debt. Tax-deductible interest (in most cases—consult your CPA).
- Cons: The new mortgage rate would be roughly 6.125%, significantly higher than their old 3.75%.
The Math Behind the Move: Why We Chose Option C
At first glance, jumping from 3.75% to 6.125% seems like a bad financial move. However, real estate finance is about the Blended Rate and Total Monthly Outflow.
Here is the breakdown we presented to the Millers:
| Category | Current Situation (Before) | New Cash-Out Refi (After) |
|---|---|---|
| Mortgage Balance | $340,000 | $470,000 (Inc. costs) |
| Interest Rate | 3.75% | 6.125% |
| Mortgage Payment (P&I) | $1,575 | $2,855 |
| Credit Card Debt Payment | $1,050 (Min + Interest) | $0 (Paid Off) |
| Personal Loan Payment | $350 | $0 (Paid Off) |
| Kitchen Remodel Funding | $0 (Still Needed) | $75,000 Cash in Bank |
| TOTAL MONTHLY OUTFLOW | $2,975 | $2,855 |
The Verdict: By refinancing, the Millers actually lowered their total monthly obligation by $120 per month while securing $75,000 in cash for their renovation.
Even more importantly, they moved $50,000 of toxic, high-interest debt (averaging 20%+) into a stable, tax-advantaged mortgage at 6.125%. This is the power of debt consolidation. If they had kept their old mortgage and tried to pay for the kitchen with a HELOC, their total monthly payments would have soared to over $4,000/month.
The Execution: Navigating the 2026 Process
Once the decision was made, we moved quickly. The Arizona market in 2026 is efficient, but underwriting standards have tightened slightly compared to the boom years.
Step 1: The Appraisal
This was the biggest hurdle. For a cash-out refinance, lenders typically allow you to borrow up to 80% of the home's value (Loan-to-Value or LTV). With a target value of $980,000, 80% would be $784,000. Since the Millers only needed a total loan of $470,000, they were well below the limit (approx 48% LTV). This "low leverage" position made them very attractive to lenders, allowing us to secure a rate slightly below the market average.
The appraiser noted the strong comparable sales in 85254, particularly highlighting the premium buyers are paying for updated homes, which validated the Miller's decision to renovate.
Step 2: Underwriting & Income
Since this was a "full doc" loan, the Millers provided W-2s and bank statements. One specific 2026 nuance: Lenders are now scrutinizing homeowner's insurance costs more closely due to rising premiums in the Southwest. We ensured their Debt-to-Income (DTI) ratio remained healthy even with the higher projected mortgage payment.
Step 3: The Closing Table
At closing, the title company handled the disbursements directly. They sent wire transfers to pay off the Visa, Mastercard, and the personal loan directly. The remaining $75,000 was wired to the Miller's checking account to commence the renovation.
The Result: A Modern Home and Financial Peace
Three months post-closing, the Millers are in a completely different financial and lifestyle position.
The Financial Win:
They are no longer bleeding cash to credit card interest. Their single mortgage payment is automated, and they have stopped stressing about juggling multiple due dates. They are effectively saving hundreds of dollars a month in interest that was previously going to credit card companies.
The Lifestyle Win:
The renovation is underway. They opted for a "desert modern" aesthetic with warm wood tones and a large quartz island. Real estate agents in the area have confirmed that a high-end kitchen remodel in 85254 typically offers an ROI of 85-90% upon resale, further cementing their equity position.
Why This Strategy Works in 2026
This case study highlights a critical lesson for Arizona homeowners: Interest rate is not the only metric that matters.
In 2026, we are seeing a "stabilization" phase. We are likely not going back to 3% rates, but we also aren't seeing the volatility of 2023. This stability allows for long-term planning. Homeowners holding onto debt to "save" a low mortgage rate are often stepping over dollars to pick up pennies.
Is a Cash-Out Refinance Right for You?
While this worked perfectly for the Millers, it isn't a one-size-fits-all solution. This strategy is best for homeowners who:
- Have significant equity (at least 30-40%).
- Are carrying high-interest consumer debt (credit cards, auto loans, personal loans).
- Plan to stay in their home for at least 3-5 more years to amortize the closing costs.
- Have a specific use for the cash (remodel, investment, debt payoff) rather than discretionary spending.
Conversely, if you have no debt and just want cash for a luxury car, a HELOC might still be the better tool despite the variable rate, as you can pay it off aggressively without losing your primary mortgage rate.
Future-Proofing the Loan
One final piece of advice we gave the Millers: Date the rate, marry the house.
If mortgage rates drop significantly in 2027 or 2028—perhaps down to the low 5% range—the Millers can refinance again (Rate & Term Refinance) to lower their monthly payment even further. By consolidating their debt now, they have cleaned up their credit utilization and improved their credit score, putting them in an even better position to qualify for future rate drops.
Are you sitting on equity in Scottsdale, Phoenix, or the East Valley? Don't let high-interest debt eat away at your wealth. Contact our team today for a custom "Blended Rate Analysis" to see if a cash-out refinance could save you money every month.
Frequently Asked Questions
Is a cash-out refinance a good idea for debt consolidation in Arizona?
How much cash can I pull out of my home in Scottsdale?
Do I have to pay taxes on the cash out from a refinance?
Jonathan Moses
Senior Loan Officer | ✅ Verified NMLS #2064741
This guide was prepared by Jonathan Moses (NMLS #2064741), the senior loan officer and founder of Roadrunner AZ Lending. With years of experience in the Phoenix and Scottsdale markets, Jonathan is dedicated to providing expert, transparent advice. Learn more about Jonathan.